

Blogs
PW Consulting: Luxury Yacht Market Hits $11.0B in 2025, Poised for 6.98% CAGR Through 2032
By PW Consulting, 2026-09-16
Navigating the Blue Horizon: Strategic Intelligence for the Global Luxury Yacht Market in 2026
The global luxury yacht industry stands at a pivotal inflection point as it moves deeper into the second half of the decade. Characterized by high net worth individual demand, complex manufacturing ecosystems, and increasingly stringent regulatory environments, the sector requires more than mere observation. It demands rigorous, data-driven strategic intelligence.
Luxury Yacht Market
This article serves as a comprehensive introduction to PW Consulting latest market research publication: the Luxury Yacht Market Report 2026–2032 . Designed for executives, investors, and industry stakeholders, this study dissects the forces shaping revenue trajectories, competitive positioning, and operational risks across the superyacht value chain. Below, we outline the strategic value proposition of this research, preview the macro-economic landscape, and demonstrate why access to the full intelligence suite is critical for 2026 decision-making.
The Macro Landscape: Growth Trajectory and Market Scale
Understanding the broad contours of the market is the first step toward informed strategy. Based on historical data from 2020 through 2025 and our proprietary forecast models extending to 2032, the luxury yacht sector has demonstrated consistent resilience and expansion, even amidst global economic volatility.
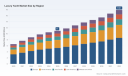
The market has evolved from a revenue base of approximately 6.58 billion USD in 2020 to an estimated 11.0 billion USD by 2025. This expansion reflects not only recovery from pandemic-era disruptions but also a structural shift in high-net-worth consumption patterns, with a marked preference for experiential luxury and asset-based wealth preservation. Looking forward, our analysis projects the global market revenue to reach 17.91 billion USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent over the forecast period. Such a rate indicates healthy organic expansion, though it also signals intensifying competition for new builds, charter inventory, and after-sales service contracts. For stakeholders, this trajectory suggests that volume-based strategies must be balanced with margin protection, as raw growth alone will not guarantee profitability in an increasingly sophisticated buyer environment.
Why This Report Matters for 2026 Decision-Makers
Strategic planning in the yacht industry cannot rely on aggregated headlines. Manufacturers, brokers, charter operators, and financial institutions need granular visibility into segmentation dynamics, regional nuances, and competitive maneuvering. Our report is engineered to provide this visibility without overwhelming decision-makers with raw data tables. Instead, it translates complex datasets into actionable strategic narratives.
Comprehensive Coverage of Build, Demand, and Application Segments
The study examines the market through multiple analytical lenses. We analyze the revenue contribution of motor yachts versus sailing yachts, highlighting how design preferences and performance requirements drive distinct supply chains and pricing architectures. The breakdown of yacht size categories—from vessels up to 50 meters to those exceeding 100 meters—reveals shifting demand among owners who increasingly seek both coastal luxury and long-range expedition capabilities.
Furthermore, the report explores application splits between personal use and commercial charters. This distinction is critical as the line between private asset ownership and revenue-generating investment blurs. Understanding the commercialization trends, including crewed charters and corporate hospitality vessels, provides insight into secondary revenue streams that can alter total lifecycle value assessments.
Regional Intelligence and Demand Geography
While the global headline figures provide the macro context, regional demand patterns dictate where investments, showrooms, and service hubs should be located. Europe remains a dominant center of gravity for both manufacturing heritage and high-net-worth buyer concentration. North America represents a significant and growing demand hub, influenced by coastal wealth clusters and regulatory frameworks specific to US imports. Meanwhile, the Asia Pacific region, Latin America, and the Middle East and Africa each present unique growth vectors with distinct client profiles, financing environments, and logistical considerations.
Our regional segmentation analysis avoids superficial generalizations. Instead, it maps demand intensity against supply chain proximity, identifying where market friction—such as import tariffs or fragmented customs regimes—may impact final pricing and delivery timelines.
Competitive Dynamics: An Oligopolistic Battlefield
The luxury yacht manufacturing sector is characterized by high barriers to entry, substantial capital requirements, and long lead times for vessel delivery. These factors have fostered a moderately concentrated landscape, where a select group of established shipyards and brands command a significant share of total revenue.
Our analysis estimates that the top three competitors collectively represent approximately 55 percent of the market, while the top five firms account for roughly 62 percent. This concentration underscores the importance of brand equity, engineering reputation, and the ability to deliver bespoke or semi-custom vessels at scale.
Key Players and Their Strategic Postures
The report provides detailed profiles of the organizations that define the competitive arena:
- Feadship (Makkum, Netherlands) continues to anchor its identity on pure custom creation, a philosophy maintained since its founding in 1949, appealing to ultra-high-net-worth clients who demand unique hull forms and interiors.
- Lürssen (Bremen, Germany) remains a premium builder of complex custom motor and sailing yachts, known for technical sophistication and large-scale project execution.
- Sunseeker (Poole, United Kingdom) leverages its position as a world-leading luxury motor yacht brand with strong emphasis on design and engineering excellence, catering to a broad spectrum of luxury buyers.
- Ferretti Group (Forlì, Italy) operates multiple luxury motor yacht lines, including the Riva and Pershing brands, blending Italian design heritage with diversified product portfolios.
- Sanlorenzo (Viareggio, Italy) and Benetti (Viareggio, Italy) both offer semi-custom and full-custom superyacht solutions, competing on flexibility, quality, and the ability to tailor vessels to specific owner preferences.
- Azimut-Benetti Group (Viareggio, Italy) delivers bespoke and semi-custom vessels, often competing on styling, performance, and integrated ownership experiences.
- Oceanco (Makkum, Netherlands) has carved a niche in advanced expedition and custom motor yachts, focusing on capability and autonomy for long-range cruising.
- Heesen Yachts (Gorinchem, Netherlands) is recognized for aluminum hybrid and custom motor yachts, emphasizing speed, efficiency, and innovative hull construction.
- Gulf Craft (Moss Point, United States) produces luxury megayachts and private cruisers, expanding the reach of American-built or assembled premium vessels.
- Tankoa Yachts (Ancona, Italy), Amels (Makkum, Netherlands), Hakvoort Shipyards (Makkum, Netherlands), and Cantiere delle Marche (Macerata, Italy) each bring specialized expertise in semi-custom designs, large motor yachts up to 100 meters, sail and motor combinations, and custom engineering.
Additionally, the report tracks emerging activity from brands such as Valhalla Boatworks (South Portland, United States), known for luxury powerboats delivering Viking-quality motor yachts, illustrating how specialized builders are capturing niche segments within the broader market.
Recent Moves and Market Signals
The competitive landscape is not static. Recent activity at major industry events underscores the pace of product innovation and brand refreshment. At the Cannes Yachting Festival in September 2025, multiple manufacturers unveiled significant launches. Groupe Beneteau introduced 19 new models and 14 world premieres, including a new Sealoft range for Jeanneau, signaling aggressive portfolio expansion. Tankoa Yachts debuted the T450 luxury yacht, Benetti presented the Class 44M, and Cantiere delle Marche showcased the Prestige M7. Each of these launches reflects strategic efforts to capture shifting buyer preferences, refresh brand relevance, and compete for delivery slots in a market where wait times and customization are key differentiators.
Luxury Furniture Market
Our report goes beyond event summaries. It evaluates how such product launches influence order pipelines, pricing power, and competitive positioning, helping readers assess which manufacturers are likely to gain or lose share in the near term.
Regulatory and Economic Headwinds: Navigating Complexity
While demand fundamentals remain positive, the operating environment is becoming more complicated. Regulatory shifts and macroeconomic pressures are reshaping cost structures, compliance obligations, and market access. The report dedicates substantial attention to these dynamics, as ignoring them can lead to erroneous forecasts and strategic missteps.
Regulatory Evolution and Safety Standards
Regulatory frameworks are tightening across multiple jurisdictions. Malta revised its Commercial Yacht Code (CYC) in 2025, with the updated provisions taking effect on 1 July 2025. This code now governs commercial yachts—typically those carrying up to 12 passengers—through modernized design, safety, manning, and welfare standards. For charter operators and owners operating under commercial registries, these changes directly affect operational compliance and cost.
At the same time, the 2026 Yacht Code took effect from 1 January 2026, applying enhanced safety requirements to all vessels of 500 GT and above. Among the notable updates are mandatory fire safety provisions for lithium-ion equipment storage. As yachts increasingly incorporate advanced battery systems and hybrid technologies, compliance with these provisions becomes a design and procurement imperative rather than an afterthought.
Environmental Pressures and Carbon Pricing
The expansion of the EU Emissions Trading System (ETS) to the maritime sector, rolled out during 2024–2025, now applies carbon pricing to fuel emissions for superyachts operating in EU ports. This development introduces a new cost dimension for operators and owners who frequently navigate European waters. While the full financial implications depend on usage patterns and emission intensities, the directional signal is clear: environmental compliance is moving from voluntary sustainability narratives to hard operational cost factors.
Trade Policy and Regional Fragmentation
Trade dynamics are also adding friction. New US tariffs of 15 percent now apply to most goods imported into the United States, increasing costs for components built outside the country destined for luxury yachts sold to American buyers. For builders that rely on cross-border supply chains, this tariff structure affects both pricing strategies and sourcing decisions. Simultaneously, EU customs rules remain fragmented as of 2026, leaving superyacht owners exposed to potential VAT billing complications on high-value transactions. This fragmentation can complicate cross-border purchases, relocation of vessels, and ownership structuring.
Our report contextualizes these regulatory and trade elements within the broader market narrative, assessing how they interact with demand elasticity, buyer geography, and shipyard sourcing strategies. The full edition provides detailed mapping of risk exposure by region and vessel category.
What You Will Gain from the Full Report
This preview has highlighted the macro trajectory, competitive structure, and regulatory context that define the current luxury yacht market. However, strategic advantage lies in the details that cannot be fully unpacked in an introduction. The complete PW Consulting report delivers:
- Granular segmentation analysis that breaks down revenue contributions, growth rates, and strategic implications across type, size, application, and region, enabling precise go-to-market and investment decisions.
- Deep-dive competitive assessments that evaluate market share movement, brand positioning, product pipeline strength, and operational capabilities of key players, including their recent launches and development trajectories.
- Scenario-based forecasting that links regulatory developments, tariff structures, and carbon pricing mechanisms to financial outcomes, helping organizations model best-case, base-case, and stress-case scenarios.
- Practical recommendations for manufacturers, brokers, charter operators, and financial institutions, covering pricing architecture, supply chain resilience, compliance planning, and market entry or expansion strategies.
- Data-driven insights on how personal use demand and commercial charter dynamics are evolving, supporting asset valuation models and fleet planning decisions.
For organizations operating in or adjacent to the luxury yacht ecosystem, the difference between reactive management and proactive strategy is access to reliable, nuanced market intelligence. This report is designed to bridge that gap.
Conclusion: Positioning for the Next Phase of Growth
The luxury yacht market is on a clear growth path, with revenue expanding from levels observed in the early 2020s toward nearly 18 billion USD by 2032 and a CAGR of 6.98 percent guiding the forecast window. Yet growth alone does not win markets. Success in 2026 and beyond will depend on the ability to interpret segmentation signals, anticipate regulatory costs, navigate trade frictions, and align product strategy with the evolving expectations of high-net-worth buyers and commercial operators.
PW Consulting Luxury Yacht Market Report provides the comprehensive intelligence necessary to make those decisions with confidence. By combining historical context, forward-looking forecasts, competitive analysis, and regulatory assessment into a single cohesive study, it equips stakeholders to move beyond assumptions and act on evidence.
To explore the full segmentation breakdowns, competitive profiles, regional intelligence, and scenario models, we invite you to access the complete report on the PW Consulting portal. The detailed data and strategic frameworks contained within are tailored for decision-makers who require precision, not generalities, as they plan for the years ahead.
For detailed analysis of this topic, please visit the official page: Luxury Yacht Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China control valve market has demonstrated consistent revenue growth from 2020 and is forecast to maintain its upward trajectory through 2035, largely fueled by industrial expansion and technological advancements in process control. Between 2020 and 2025, revenues rose sharply as infrastructure investments peaked and automation accelerated. Post-2025, steady economic development and regulatory mandates are expected to drive continued demand, though at a moderate CAGR. The market is projected to surpass USD 1,500 Million by 2035, reflecting its strategic importance in China's industrial modernization agenda.
Read More - https://bussinessinsights.com/research-report/china-control-valve-market
The oil & gas sector continues to represent the largest share of the China control valve market in 2025, driven by ongoing investments in refining, petrochemicals, and LNG infrastructure. Water & wastewater treatment is emerging as a rapidly growing application, reflecting intensified environmental policies and urbanization. The food & beverage, energy, and pharmaceutical industries are also significant contributors. Market players are increasingly tailoring valve solutions to meet the stringent process safety and hygiene requirements of these sectors, resulting in a highly diversified application landscape.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-control-valve-market
Frequently Asked Questions
Who are the key players in China Control Valve Market industry?
The top players in the China Control Valve Market are Emerson Electric Co., Flowserve Corporation, IMI plc, Zhejiang Sanhua Intelligent Controls Co., Ltd., and Shanghai Automation Instrumentation Co., Ltd. These companies lead the market through advanced product innovations, extensive distribution networks, and strong client bases across various industrial applications.
What is the China Control Valve Market growth?
The China Control Valve Market has seen robust growth, with a CAGR of over 6% in recent years. Growth is driven by Zhejiang Sanhua Intelligent Controls expanding into smart valve solutions, catering to increasing automation demands in manufacturing and energy sectors across China.
Which segment accounted for the largest China Control Valve Market share?
The oil and gas application segment holds the largest market share in the China Control Valve Market. This is due to significant investments in refining, petrochemical, and LNG projects, demanding advanced and reliable control valves for efficient process management and meeting stringent regulatory requirements.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The NVH testing market in China is projected to rise consistently through 2035, beginning at approximately USD 870 million in 2020 and reaching an estimated USD 2,650 million by 2035. This growth is underpinned by rapid adoption in the automotive and electronics industries, as well as ongoing investments in testing technology to meet both consumer and regulatory demands. Significant advancements in testing hardware and software platforms are expected to push annual revenues higher, particularly as electric mobility and smart manufacturing proliferate.
Read More - https://bussinessinsights.com/research-report/china-nvh-testing-market
The automotive sector dominates the application share of China's NVH testing market in 2025, reflecting the nation's position as the world's largest auto market and the rapid electrification of vehicles. Industrial applications represent the next largest share, benefitting from intensified efforts to comply with health and safety standards governing workplace noise and vibration. The aerospace application is advancing steadily, spurred by increasing aircraft production and emphasis on passenger comfort.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-nvh-testing-market
Frequently Asked Questions
Who are the key players in China NVH Testing Market industry?
The top five players in the China NVH Testing Market are Brüel & Kjær, Siemens Digital Industries Software, Head Acoustics GmbH, National Instruments Corporation, and m+p international. These companies lead the sector with extensive product portfolios, advanced NVH solutions, and strong partnerships within China's automotive and industrial markets.
What is the China NVH Testing Market growth?
The China NVH Testing Market is experiencing robust growth, driven by rising vehicle production and stricter regulations for noise and vibration control. For instance, Brüel & Kjær has reported increased demand for their testing systems in China’s electric vehicle segment, supporting market expansion in recent years.
Which segment accounted for the largest China NVH Testing Market share?
The automotive segment accounted for the largest share of the China NVH Testing Market. Growing investments by OEMs in vehicle comfort and safety, alongside stringent government standards for noise and emissions, have propelled NVH testing solutions used in passenger and commercial vehicles.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting Forecasts Residential Interior Door Market to Hit $20.95 Billion by 2032 at 5.5% CAGR
By PW Consulting, 2026-09-16
Navigating the Residential Interior Door Market: Strategic Intelligence for 2026 Decision-Makers
The residential interior door market is undergoing a quiet but significant transformation. No longer viewed as a commoditized building component, interior doors are increasingly recognized as critical elements of home performance, privacy, acoustics, design identity, and sustainability compliance. As construction cycles recover, renovation activity accelerates, and consumer expectations evolve toward smarter, healthier, and more customized living spaces, manufacturers, distributors, contractors, and private investors face a complex landscape that rewards foresight over guesswork.
Pw Consulting’s latest Residential Interior Door Market study is designed to cut through this complexity. Rather than offering superficial trends, the report delivers a structured, execution-ready intelligence framework that connects macro market trajectories with granular competitive positioning, segment-specific growth vectors, and regulatory-driven shifts in material and manufacturing preferences. For executives formulating 2026 operating plans, capital allocation strategies, and product roadmaps, this research serves as both a diagnostic tool and a forward-looking navigation system.
Market Trajectory: A Decade of Steady Expansion with 2026 as a Strategic Inflection Point
Historical performance and forward-looking projections place the residential interior door category on a consistent growth path. The market has expanded from approximately $9.95 billion in 2020 to an estimated $14.3 billion in 2025, reflecting resilient demand across housing turnover, remodeling cycles, and design-led replacement programs. Looking ahead, the study maps the market toward a projected valuation exceeding $20.9 billion by 2032, anchored by a compound annual growth rate of 5.5 percent throughout the forecast window.
These figures are not merely aggregate indicators; they reflect underlying momentum that varies meaningfully across product architectures, application contexts, geographic demand centers, and buyer segments. For leadership teams, the strategic implication is clear: growth is real, but it is unevenly distributed. Companies that treat the category as a uniform market risk misallocating resources, entering overheated segments, or overlooking high-margin niches. Exact regional shares, application-level breakdowns, and material-specific revenue contributions are addressed in depth within the full report, where they are modeled alongside pricing elasticity, channel dynamics, and competitive intensity to reveal where profitable expansion is most achievable.
2026 Dynamics: What Is Shaping Demand, Pricing, and Go-to-Market Strategy
Several concurrent forces are redefining how residential interior doors are specified, manufactured, and sold. Understanding their interaction is essential for strategic planning.
Sustainability and Material Standards as Demand Drivers
Responsibly sourced wood, low-VOC finishes, and certified manufacturing practices are transitioning from differentiators to baseline expectations. Buyers, retailers, and increasingly regulated building programs are prioritizing products that align with broader environmental and indoor-air-quality goals. At the same time, updated energy-efficiency considerations and evolving material standards are elevating interest in advanced composite formulations and sustainable door cores. The report dissects how these preferences are reshaping sourcing economics, product architecture choices, and brand positioning across competing portfolios.
Renovation Activity and Housing Demand as Volume Anchors
A robust pipeline of home improvement projects and sustained housing activity continues to underpin steady transactional volume for interior door products. While new-build cycles fluctuate, the renovation channel has proven more resilient, often favoring variety, finish customization, and solution-based selling. The study evaluates how renovation-led demand differs from new-construction demand in terms of order characteristics, specification behavior, and competitive vulnerability, enabling readers to calibrate sales and inventory strategies accordingly.
Trade Friction, Sourcing Strategy, and Cost Pressure
Trade restrictions on imported wood and door components remain a persistent variable in pricing and supply planning. For U.S.-based manufacturers, these dynamics influence raw material availability, finished-goods cost structures, and the relative attractiveness of domestic versus imported supply chains. The analysis examines how leading players are adapting their procurement footprints and product mix decisions in response, and where margin protection is becoming a competitive differentiator.
Smart-Home Integration and Evolving Specification Behavior
Consumer expectations are increasingly shaped by the broader smart-home ecosystem and the desire for doors that contribute to acoustic comfort, privacy, and integrated home functionality. This is not always a matter of embedded electronics; it increasingly involves specification alignment, finish coordination, sound-reduction capabilities, and design compatibility with connected-home aesthetics. The report assesses how these expectations are influencing product development priorities and retail specification strategies.
Segmentation Architecture: Where the Growth Dividends Are Concentrated
One of the study’s core analytical strengths is its segmentation framework. The market is evaluated across multiple dimensions that matter operationally: material preferences, application contexts, and regional demand centers. Each axis reveals a distinct competitive logic.
Material strategies continue to define both cost structure and brand identity. Wood remains a foundational reference point for premium positioning and custom specification, while composite alternatives are gaining traction where durability, consistency, and sustainability credentials intersect. Glass, steel, and other specialty materials occupy targeted niches tied to design statements, acoustic requirements, or specific residential applications. Rather than presenting static shares, the report layers these material preferences against pricing behavior, channel fit, and regional demand intensity to expose where category leadership is being contested and where white space remains.
Application-level analysis is equally critical. Interior doors are specified differently depending on whether they serve private sleeping areas, high-use transitional spaces, moisture-adjacent environments, or secondary rooms with distinct functional and aesthetic requirements. Each application carries its own drivers for privacy, acoustics, moisture resistance, style coordination, and replacement frequency. The study maps these nuances to reveal which applications exhibit the strongest renewal cycles, which are most sensitive to design trends, and which offer the most attractive unit economics for manufacturers and distributors.
Regional demand patterns further complicate the picture. Mature markets display different growth mechanics than emerging demand centers, and local building norms, renovation intensity, trade exposure, and channel maturity all shape how products are positioned and sold. The complete report quantifies these regional dynamics with sufficient granularity to support market-entry decisions, distribution planning, and localized product strategy without revealing the precise splits here, preserving the analytical exclusivity that enterprise buyers expect.
Residential Interior Door Market
Competitive Landscape: Differentiation in a Moderately Concentrated Market
The market structure reflects a moderate level of concentration, with the top three players accounting for approximately 35 percent of revenue and the top five reaching roughly 42 percent. This indicates that while scale players hold meaningful share, a substantial portion of the market remains accessible to specialized manufacturers, regional champions, and design-led brands that compete through customization, craftsmanship, and portfolio breadth.
The competitive set illustrates the diversity of strategic approaches now defining the category. JELD-WEN continues to leverage a broad product architecture spanning wood, composite, and molded interior doors, with solid-core options positioned around sound reduction and consistent specification. Masonite complements this landscape with premium fiberglass and wood offerings, including series designed for elevated aesthetics and residential performance. TruStile Doors differentiates through custom stile-and-rail interiors that span premium MDF, wood, glass, resin, leather, and metal options, appealing to buyers seeking tailored design outcomes. Simpson Door Company draws on a long heritage of handcrafted custom wood doors, reinforcing craftsmanship as a competitive asset. Lynden Door aligns with sustainability-minded procurement through green-certified materials and custom wood offerings, while Rogue Valley Door emphasizes interactive design tools that support specification and customization. Woodgrain competes on breadth of design expression through stile-and-rail and router-carved interiors with extensive design libraries. Andersen Windows and Doors and Pella Corporation integrate interior door offerings within broader residential portfolios, using cross-category relationships as a commercial advantage. ProVia positions professional-class interior doors with customizable cores and overlays, appealing to specification-driven projects.
Recent corporate activity reinforces the strategic tempo of the category. In early 2026, Therma-Tru introduced new ¾-Lite Shaker interior doors and sidelites, signaling continued interest in refined, specification-friendly designs. Later in the year, Masonite showcased its Calden three-panel interior door at a major builders’ event, highlighting the ongoing push toward visually differentiated, multi-panel configurations that resonate with design-led residential projects. These launches are not isolated product updates; they are indicators of where manufacturers are placing bets on aesthetics, functionality, and channel appeal. The full report contextualizes each major competitor’s positioning, product emphasis, and strategic vulnerabilities, enabling readers to benchmark their own portfolios and identify adjacency opportunities without relying on generic competitive summaries.
What the Report Delivers: A Practical Toolkit for 2026 Strategy
This study is built for action. It is structured to help leadership teams answer the questions that matter most when planning product investments, channel expansion, pricing strategy, and competitive response. The report includes:
- A demand-and-supply assessment that connects historical performance to forward projections, with scenario-based views that account for renovation intensity, housing activity, and trade-related cost pressure.
- Multi-dimensional segmentation analysis covering material categories, application contexts, and regional demand patterns, designed to reveal where growth is strongest, where margins are most defensible, and where competitive intensity is rising.
- A competitive profiling section that evaluates leading manufacturers by product emphasis, differentiation logic, and strategic positioning, providing a comparative lens for portfolio planning and market-entry evaluation.
- An examination of market dynamics, including sustainability mandates, certification expectations, material sourcing constraints, and smart-home-aligned specification trends, framed in terms of commercial impact rather than abstract observation.
- Strategic implications for manufacturers, distributors, builders, and investors, with guidance on where to concentrate resources, which customer segments warrant deeper engagement, and how to align product roadmaps with emerging demand signals.
Throughout, the analysis maintains a disciplined focus on decision utility. Figures, shares, and forward estimates are presented with enough context to support judgment, but the most sensitive segmentation data and regional revenue distributions are reserved for the full report. This approach ensures that the complete intelligence product remains a proprietary asset for teams that need to make specific capital, sourcing, and positioning decisions with confidence.
Why This Study Matters for 2026 Planning
The residential interior door market is not defined by a single megatrend. It is shaped by the interplay of renovation economics, material sustainability expectations, trade-driven cost dynamics, design-led specification behavior, and a competitive field that rewards both scale and specialization. In that environment, generalization is a liability. Winning strategies require clarity on which applications are expanding, which materials are gaining pricing power, which regions offer the best risk-adjusted opportunity, and how competitors are translating product innovation into commercial advantage.
Pw Consulting’s Residential Interior Door Market report is intended to provide that clarity. It gives executives a structured, evidence-based foundation for 2026 decision-making, while preserving the deeper segmentation and competitive intelligence needed to convert insight into action. For organizations that need to know not only where the market is heading, but where to place bets now, the full study offers the granularity, benchmarking, and strategic framing necessary to move from awareness to execution.
The market trajectory is visible; the competitive and segmentation details that determine success are not. Accessing the complete analysis is the next step for teams ready to align their 2026 plans with the realities of a maturing, increasingly differentiated residential interior door category.
Wood Interior Doors Market
For detailed analysis of this topic, please visit the official page: Residential Interior Door Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Market revenue has shown exponential growth since 2020, rising from $27,000 million in 2020 to an estimated $108,500 million in 2025, driven by EV proliferation, energy storage adoption, and swelling exports. Projections indicate the market may surpass $325,000 million by 2035, highlighting China's global dominance in lithium-ion battery manufacturing and innovation. Market momentum is expected to continue, fueled by ongoing R&D investments, capacity expansion, and digital transformation of battery value chains.
Read More - https://bussinessinsights.com/research-report/china-lithium-ion-battery-market
Automotive applications dominate market share in China, as the country aggressively transitions to electric mobility with government backing. Consumer electronics, including mobile devices and laptops, remain a steady segment, while industrial and energy storage applications are on a rapid rise as the nation ramps up renewables and smart grid technology. The chart demonstrates the decisive lead of automotive applications, confirming the impact of EV megatrends on battery demand.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-lithium-ion-battery-market
Frequently Asked Questions
Who are the key players in China Lithium-ion Battery Market industry?
The key players in China’s lithium-ion battery market include CATL, BYD, LG Energy Solution, CALB, and EVE Energy. CATL leads the industry as the largest battery manufacturer globally, while BYD is recognized for integrating battery production with electric vehicles. LG Energy Solution and CALB drive innovation, and EVE Energy specializes in high-performance batteries.
What is the China Lithium-ion Battery Market growth?
China's lithium-ion battery market has witnessed robust growth, driven by increasing electric vehicle adoption and energy storage solutions. For example, in 2023, CATL announced a 30% production capacity expansion in response to surging EV demand, reflecting a double-digit industry growth rate year over year.
Which segment accounted for the largest China Lithium-ion Battery Market share?
The electric vehicle (EV) application segment holds the largest market share in China’s lithium-ion battery market. Accelerated EV adoption, favorable government policies, and continuous advancements by manufacturers like BYD and CATL make the automotive sector a dominant force in overall battery demand.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
Market revenues have grown significantly, reflecting rising adoption across every major segment. In 2025, total revenue is projected at USD 12,800 Million, up from USD 8,400 Million in 2020. Onward from 2025, the market is forecasted to demonstrate a steady CAGR of 6.2%, reaching USD 23,980 Million by 2035. The rapid proliferation of smart cameras and integration into industrial automation and healthcare are expected to be key revenue drivers. Market leaders are increasingly focused on new product launches and strategic alliances to consolidate growth.
Read More - https://bussinessinsights.com/research-report/china-camera-technology-market
Consumer electronics continue to dominate the China Camera Technology Market in 2025, driven by robust demand for smart devices, smartphones, and personal cameras. Automotive applications are a rapidly growing segment due to the surge in ADAS technologies. Healthcare imaging, boosted by technological advancements and telemedicine trends, secures an increasing portion of the market, outranking industrial and defense applications. Industrial use cases, alongside aerospace and security, form the backbone of the remaining application segments. The interplay of new-use cases and regulatory requirements is poised to further diversify application areas.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-camera-technology-market
Frequently Asked Questions
Who are the key players in China Camera Technology Market industry?
The key players in China’s camera technology market include Hikvision (leading in surveillance), Dahua Technology (major in security cameras), Huawei (notable for high-end smartphone cameras), Xiaomi (affordable smartphones with advanced camera tech), and Sunny Optical Technology (key supplier of camera lenses and modules).
What is the China Camera Technology Market growth?
The China Camera Technology Market has witnessed steady growth, fueled in 2023 by rising security concerns and smartphone innovations. For example, Huawei’s partnership with Leica has boosted demand for premium smartphone cameras. The market is projected to grow at a CAGR of over 7% through 2028.
Which segment accounted for the largest China Camera Technology Market share?
The surveillance and security application segment holds the largest share of the China Camera Technology Market, driven by widespread adoption of CCTV across cities, businesses, and public infrastructure. Hikvision and Dahua Technology have led large-scale deployments, contributing to the segment’s dominance.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Smart Vending Machines Market Hits $8.82 Billion in 2025, Projecting 10.6% CAGR to 2032
By PW Consulting, 2026-09-16
The Smart Vending Machines Market in 2026: Strategic Intelligence for Enterprise Decision-Makers
The global smart vending machines market is undergoing a structural transformation that goes far beyond the traditional convenience retail model. As automated retail intersects with artificial intelligence, contactless payment infrastructure, and mission-critical dispensing in healthcare and public health settings, organizations face a pivotal moment. This research provides the strategic foundation needed to make informed capital allocation, partnership, and market-entry decisions across the 2026-2032 forecast horizon.
Worldwide Vending Machine Payment System Market
For executives evaluating whether to deploy, invest in, or partner with smart vending infrastructure, the question is no longer whether automation will reshape point-of-sale access. The question is where value will concentrate, which applications will command pricing power, and how regulatory and reimbursement dynamics will shape viable business models. This report has been designed to answer those questions with the granularity and commercial relevance that enterprise strategy teams require.
A Market Built on Accelerated Adoption and Structural Tailwinds
Over the historical review period from 2020 through 2025, the smart vending machines market demonstrated consistent, compounding growth. Total revenue expanded from approximately 5.32 billion USD in 2020 to 8.82 billion USD by 2025, reflecting an industry that has moved beyond early experimentation into mainstream operational integration. The growth trajectory is not merely incremental. It is supported by a convergence of demand-side forces: consumer expectation for 24/7 autonomous access, enterprise demand for inventory visibility, and the emergence of specialized dispensing use cases in medical and public health environments.
Looking forward, the forecast period from 2026 through 2032 projects continued expansion at a CAGR of 10.6 percent, with market revenue reaching 10.08 billion USD in 2026 and climbing to 18.09 billion USD by 2032. These figures reflect a market that is growing through both organic retail automation and the diversification of vending into strategic, non-traditional endpoints. For decision-makers, the strategic implication is clear: this is a market where timing and positioning matter. The organizations that act with a precise understanding of where growth is accelerating, and why, will be better placed to capture share and avoid misallocated capital.
It is worth emphasizing that the headline figures only tell part of the story. Behind the aggregate numbers lies a multidimensional landscape shaped by product category performance, deployment environments, regional maturity, and the regulatory context in which automated dispensing operates. The full report isolates these dimensions so that strategy teams can move from directional awareness to targeted action.
What the Report Delivers: Operational Intelligence, Not Generic Observation
This market research has been constructed for practitioners who need to make investment, procurement, partnership, and rollout decisions under real commercial constraints. Rather than offering a high-level summary, the study provides a structured analytical framework that connects market sizing to market logic. The following components are central to the analysis:
- Historical revenue performance and forward-looking market sizing across the 2026-2032 forecast window, enabling multi-year planning and scenario-based budgeting
- Segment-level evaluation across product categories and application environments, with attention to how demand patterns differ by context and what that means for deployment strategy
- Regional market structure and maturation pathways, helping organizations understand where adoption is advanced, where growth momentum is strongest, and where infrastructure or regulatory conditions shape opportunity
- Competitive positioning analysis that examines the strategies, capabilities, and recent moves of leading participants across commercial vending, healthcare dispensing, and public health applications
- Market dynamics assessment covering technological enablement, operational requirements, reimbursement behaviors, and regulatory classification considerations that influence market entry and scaling
- Practitioner-oriented synthesis designed to translate analytical findings into strategic options for vendors, investors, facility operators, and public-sector stakeholders
The intent is to provide a usable decision-support tool. Whether your interest lies in evaluating a new product rollout, assessing a potential acquisition target, identifying underserved application areas, or mapping competitive vulnerability, the report is built to connect quantitative structure with qualitative commercial reasoning.
Competitive Landscape: A Market Shaped by Diverse Motivations
One of the most strategically important features of the smart vending machines market is the diversity of participants and motivations shaping its evolution. The competitive space is not dominated by a single business model or end-use logic. Instead, it brings together commercial technology providers, healthcare institutions, academic and public-health operators, and community-facing organizations, each with distinct objectives and deployment strategies.
Recent activity illustrates this divergence clearly. In the commercial technology segment, providers are advancing AI-enabled platforms that emphasize real-time inventory monitoring, contactless payment integration, and flexible placement models for businesses and healthcare facilities. These developments signal a shift toward smarter operational control, lower friction for end users, and more adaptable economics for site partners. At the same time, healthcare and public-health institutions are expanding automated dispensing solutions for time-sensitive, access-critical needs, including overdose prevention supplies and wellness resources.
Several developments from late 2025 through early 2026 highlight this dual trajectory. A commercial provider expanded its AI-powered smart vending platform with enhanced inventory monitoring and contactless payment capabilities, reinforcing the growing importance of software-defined vending operations. In parallel, health systems and public health departments have advanced the deployment of naloxone dispensing machines across hospital campuses and community sites, with early installations reporting substantial utilization within their first months of operation and subsequent expansion to additional locations. These deployments show that automated vending is increasingly embedded in mission-driven contexts where availability, anonymity, and 24/7 access are core to the value proposition.
Smart Vending Machines Market
This landscape has meaningful implications for market structure. The level of concentration suggests that while leading players hold significant share, there remains room for specialization, regional deployment advantages, and differentiated application expertise. Enterprise stakeholders therefore need to assess competitors not only by scale, but by application fit, regulatory readiness, partnership model, and operational sophistication. The report examines these competitive dimensions in depth, enabling readers to understand where incumbency advantages exist and where targeted entrants may find viable openings.
Regulatory and Operational Dynamics That Will Shape Strategy
Smart vending strategy cannot be separated from the operational and regulatory environment in which equipment is deployed. In particular, the medical and public-health dimensions of automated dispensing introduce requirements that differ substantially from commercial convenience retail. Automated dispensing units used in medical contexts are classified as Class II medical devices by the U.S. Food and Drug Administration and require 510(k) clearance. This classification is not a minor compliance detail; it affects development timelines, product validation, market access, and the cost structure of healthcare-oriented vending solutions.
At the same time, reimbursement and procurement behaviors are evolving. Hospitals and clinics are increasingly deploying automated dispensing units for over-the-counter medications, personal protective equipment, and wellness products, indicating a broader institutional acceptance of vending as an operational tool rather than a novelty. In the public-health space, harm reduction vending machines for naloxone and related supplies operate under state and county public health guidelines, with basic dispensing arrangements not requiring additional federal reimbursement updates. These dynamics create an environment in which compliance readiness, institutional alignment, and deployment flexibility can be as important as hardware performance.
Infrastructure realities also shape opportunity. Vending placements are not uniform in content or economics. Even within adjacent markets, product mix and site-specific utilization patterns can diverge significantly, influencing revenue potential and machine design. For organizations planning market expansion or portfolio optimization, these factors underscore the need to evaluate each opportunity through the appropriate operational lens. The full report examines these dynamics as part of a broader integrated view, so that strategy teams can incorporate regulatory exposure, procurement behavior, and site-level complexity into their planning assumptions.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment demands more than awareness of top-line growth. Enterprises are being asked to evaluate where to commit capital, which deployment models are defensible, how to interpret competitive moves across both commercial and health-facing segments, and what regulatory pathways will define feasible scale. A market expanding toward the projected 2032 revenue level will not reward undifferentiated participation. It will reward organizations that can align their strategy with the underlying structure of demand, the economics of deployment, and the compliance realities of the application areas they pursue.
This report is designed to support exactly that kind of strategic clarity. It translates market structure into actionable perspective: where growth is concentrated, how applications differ in their value logic, what distinguishes leading operators in their respective domains, and which dynamics are likely to shape the next phase of market evolution. By integrating historical evidence, forward-looking sizing, competitive intelligence, and operational context, the study gives decision-makers a more reliable foundation for planning than headline figures alone can provide.
Access the Full Strategic Assessment
The analysis presented here outlines the strategic importance of the smart vending machines market and the essential questions this research addresses. However, the full report goes further. It provides the segmented evaluation, competitive detail, regional maturation context, and operational dynamic mapping that organizations need before making investment or deployment commitments. For strategy, operations, and commercial leadership teams preparing for 2026 and beyond, the complete market intelligence is essential.
To access the full dataset, segmentation evidence, competitive profiles, and application-specific strategic implications, visit the source page for the complete Smart Vending Machines Market research. The complete report is designed to support concrete decision-making, from market-entry assessment to partnership evaluation and deployment prioritization.
For detailed analysis of this topic, please visit the official page: Smart Vending Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
China’s smart lock market revenue is projected to grow from USD 870 Million in 2020 to almost USD 4,890 Million by 2035. The market shows steady annual growth as consumer acceptance of smart security solutions expands. While 2025 marks a milestone year with revenues crossing USD 2,380 Million, driven by post-pandemic digitalization and rapid urban infrastructure projects, the trend remains positive through 2035. Continuous innovation and entry of international brands are expected to reinforce double-digit CAGR over the forecast period, positioning China among the global smart lock market leaders.
Read More - https://bussinessinsights.com/research-report/china-smart-lock-market
The residential segment leads the market with 48% share in 2025, propelled by rapid smart home adoption, urbanization, and safety awareness. The commercial sector holds 25%, driven by business upgrades for employee and asset protection. Hospitality applications follow at 12% as hotels invest in digital access solutions for guest experience enhancement. Government and industrial sectors contribute 8% and 5%, respectively, with enterprises making up the remaining 2%. This snapshot underscores residential as the fastest-growing use case while highlighting the ongoing digital transformation in commercial and hospitality environments.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-smart-lock-market
Frequently Asked Questions
Who are the key players in China Smart Lock Market industry?
The top 5 players in the China Smart Lock Market include Xiaomi, Huawei, Kaadas, Dessmann, and Samsung. These companies lead the market through advanced technology integration, extensive distribution networks, and strong brand presence. Xiaomi and Huawei particularly stand out for innovation and smart home ecosystem compatibility.
What is the China Smart Lock Market growth?
The China Smart Lock Market has witnessed robust growth, with an estimated CAGR above 15% in recent years. Xiaomi's launch of AIoT-enabled smart locks in 2023 drove market expansion by integrating intelligent security features and seamless connectivity within its popular smart home platform.
Which segment accounted for the largest China Smart Lock Market share?
The residential segment holds the largest market share in the China Smart Lock Market. Growing urbanization and consumer demand for enhanced home security have fueled adoption of smart locks for apartments and private homes, making residential applications the most dominant segment.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting Proline Market Report: $595.9M in 2025, Projected $907.91M by 2032, 6.65% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the L-Proline Market: Navigating Growth and Complexity in 2026 and Beyond
The global amino acid landscape is undergoing a structural transformation, driven by shifting consumer preferences, evolving pharmaceutical demands, and increasingly complex supply chain economics. At the center of this evolution lies L-proline, a non-essential amino acid that has quietly transitioned from a specialized biochemical intermediate to a strategic commodity with broad industrial, nutritional, and therapeutic applications. As enterprises recalibrate their market positioning and supply chain resilience strategies for the coming years, decision-makers require more than surface-level industry commentary. They need granular, forward-looking intelligence grounded in rigorous primary research and validated market modeling.
Our newly released Proline Market report delivers precisely that. Designed for executives, strategy planners, procurement leaders, and investment analysts, this study maps the trajectory of the global L-proline sector across a comprehensive historical and forecast horizon. The findings illuminate not only where the market has been, but where it is structurally headed, providing a decision-ready framework for navigating volatility, capturing emerging demand, and executing competitive positioning with precision.
The 2026 Decision Imperative: Why Timing and Context Matter
Market entry, capacity expansion, partnership formation, and procurement strategy all depend on accurate contextual awareness of macroeconomic and sector-specific dynamics. For L-proline, the convergence of several forces creates a uniquely critical planning window for 2026. Post-pandemic supply chain recalibration has forced manufacturers to reevaluate sourcing dependencies, while rising demand for non-animal-derived ingredients, sports nutrition formulations, and pharmaceutical intermediates has accelerated product development cycles across multiple downstream industries.
The structural shift toward plant-based and fermentation-derived amino acid production continues to reshape cost architectures and competitive moats. Simultaneously, regulatory scrutiny around raw material sourcing, manufacturing transparency, and quality standardization is elevating compliance from a back-office function to a boardroom priority. In this environment, strategic decisions made without a clear view of market velocity, concentration patterns, and application-level demand trajectories carry heightened risk.
Our analysis is calibrated to this reality. By anchoring projections in a multi-year historical baseline and extending the forecast through 2032, the report provides a disciplined, evidence-based pathway for leaders who must act decisively rather than speculate.
Proline Market
Market Trajectory and Structural Signals
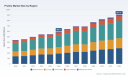
The global L-proline market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately $441 million in 2020 to an estimated $596 million in 2025. This growth reflects sustained demand across health and dietary supplement formulations, animal feed nutrition, and pharmaceutical synthesis pathways. Looking ahead, the market is projected to advance at a compound annual growth rate of 6.65 percent, reaching a valuation of roughly $643 million in 2026 and continuing its upward trajectory toward approximately $908 million by 2032.
Several structural signals underpin this momentum. First, downstream demand for amino acid-enabled formulations has broadened beyond traditional food and beverage applications. Nutritional science advancements, clinical research into amino acid metabolism, and consumer wellness trends have collectively expanded the addressable market for proline-based compounds. Second, manufacturing innovation—particularly in fermentation efficiency, strain optimization, and downstream purification—has improved yield economics and expanded grade flexibility for industrial buyers. Third, manufacturing geography continues to evolve, with production capacity increasingly distributed across major industrial corridors to mitigate single-region risk exposure.
For strategic planners, these trends carry actionable implications. Procurement teams must assess whether incumbent suppliers can sustain cost competitiveness as fermentation technology scales. Product developers need visibility into grade availability, purity specifications, and regulatory status across target applications. Investors and corporate development teams require clarity on concentration dynamics, capacity expansion signals, and the pace at which emerging players can scale. Our report addresses each of these dimensions with targeted analysis designed for execution.
Worldwide Prolactin Market
What the Proline Market Report Delivers
This study is engineered for practical use, not academic abstraction. It provides a complete analytical architecture that organizations can integrate directly into forecasting models, market entry evaluations, competitive benchmarking, and supply chain planning workflows. The report covers:
- Historical performance tracking (2020–2025): Year-over-year revenue progression, volume and value trends, and macroeconomic demand drivers that shaped the baseline period.
- Forward-looking forecast (2026–2032): Market size projections, growth rate trajectories, and structural inflection points that decision-makers should monitor as planning horizons extend.
- Type segmentation analysis: A detailed comparison of plant-based and animal-based proline supply streams, including production methodology distinctions, grade suitability, cost structures, and demand migration patterns across end-use sectors.
- Application-level demand mapping: Cross-sector evaluation of how proline is deployed in health and dietary supplements, animal feed, and pharmaceutical formulations, with emphasis on consumption drivers, formulation trends, and regional purchasing behavior.
- Regional market intelligence: Assessment of demand concentration, supply chain geography, trade dynamics, and localization trends across key industrial markets, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa.
- Competitive landscape profiling: Detailed company profiles, operational focus areas, production capabilities, and strategic positioning of leading manufacturers and emerging participants.
- Concentration and competitive intensity metrics: Structured analysis of market share distribution among top-tier players, indicating where consolidation pressure exists and where fragmentation creates entry or disruption opportunities.
Each section is designed to enable direct integration with internal strategy processes. Whether your team is evaluating supplier diversification, assessing a potential M&A target, modeling product launch scenarios, or stress-testing cost assumptions against raw material volatility, the report provides a defensible foundation for those decisions.
Competitive Dynamics and the Manufacturing Frontier
The L-proline competitive landscape reflects a blend of established multinational amino acid producers, specialized fermentation manufacturers, and regional players with strong downstream integration. The market’s top three participants collectively account for approximately 48.5 percent of revenue, while the top five extend their combined share to roughly 62.3 percent. This concentration profile indicates a market with clear incumbency advantages in scale, process know-how, and downstream customer relationships, but also suggests room for competitive repositioning as regional capacity expands and application-specific demand fragments.
Leading manufacturers demonstrate distinct strategic orientations. Ajinomoto Co., Inc., headquartered in Tokyo, Japan, has built its proline capability around industrial-scale fermentation processes designed for bulk amino acid supply across food, pharmaceutical, and nutrition channels. Evonik Industries AG, based in Essen, Germany, positions L-proline as a non-animal-derived, non-essential amino acid available in multiple industrial grades, serving feed, pharmaceutical, and specialty applications. Meihua Holdings Group Co., Ltd., operating from China, leverages corn fermentation routes to supply proline as an upstream raw material for human medical purposes, sports nutrition food, and special medical applications. KYOWA HAKKO BIO CO., LTD., also based in Tokyo, focuses on amino acid manufacturing including related proline compounds through innovative industrial fermentation methods.
Regional production capability continues to deepen. Sichuan Tongsheng Amino Acid Co., Ltd. manufactures L-proline as part of a broader amino acid portfolio targeting food, pharmaceutical, and animal nutrition markets. Zhejiang NHU Co., Ltd. produces L-proline through fermentation for use in the food industry, human medical purposes, and pharmaceutical intermediates. Shijiazhuang Jirong Pharmaceutical Co., Ltd. supplies L-proline as upstream raw material for drugs treating chronic diseases and related pharmaceutical applications. Together, these participants illustrate how proline manufacturing is not only a commodity play but also a capability-dependent business where fermentation efficiency, grade versatility, and downstream integration shape competitive durability.
Strategic buyers and competitors should pay close attention to how these manufacturers differentiate on grade availability, scale economics, supply reliability, and regulatory alignment. In a market where certain amino acids have become increasingly problematic due to high inclusion rates, elevated pricing, limited global production volumes, or manufacturing complexity, proline’s relative positioning depends on continued process optimization and supply chain transparency. The report provides structured evaluations that help organizations determine which suppliers can support long-term contractual commitments and which represent tactical sourcing options under specific demand scenarios.
Raw Material Pressures and the Cost Architecture Reality
No analysis of the L-proline market is complete without addressing input-side economics. Amino acid manufacturing remains highly sensitive to feedstock pricing, fermentation yield variability, downstream purification costs, and logistics exposure. Industry assessments have highlighted that six amino acids—serine, glutamine, asparagine, histidine, proline, and arginine—have emerged as particularly challenging due to a combination of high inclusion rates, elevated prices, low global production volumes, and manufacturing complexity.
This context matters because cost pressure is rarely uniform across the amino acid portfolio. For proline specifically, competitive advantage increasingly hinges on production efficiency, feedstock flexibility, and the ability to deliver consistent grade quality at scale. Organizations that rely on proline as an upstream input for pharmaceutical synthesis or nutrition formulations must understand how cost volatility transmits through their supply chain and where strategic buffers, alternative sourcing arrangements, or specification adjustments can preserve margin integrity.
Our report integrates these dynamics into the broader market framework, examining how raw material exposure, production complexity, and regional capacity trends interact with pricing behavior and buyer negotiation leverage. Rather than offering static cost snapshots, the analysis maps the structural variables that will shape procurement economics and manufacturing competitiveness over the forecast period.
Why This Report Is Built for 2026 Strategy Execution
Decision-making in 2026 will be shaped by the intersection of demand expansion, supply chain recalibration, technological advancement in fermentation, and increasing transparency requirements across food, nutrition, and pharmaceutical value chains. In that environment, organizations need intelligence that is simultaneously broad enough to capture macro momentum and precise enough to guide category-level actions.
The Proline Market report is structured to meet that standard. It combines historical validation with forward-looking forecasting, maps competitive and application-level dynamics, and provides the analytical scaffolding necessary to translate trend observation into strategic action. More importantly, it preserves strategic discretion: by identifying where the largest decision-relevant opportunities and risks reside, it helps leaders prioritize the questions that matter most before committing capital, capacity, or commercial resources.
Access the Full Intelligence Architecture
The complete Proline Market report extends well beyond the strategic overview presented here. It contains detailed segmentation breakdowns, regional demand and supply mappings, company-level capability assessments, and forecast scenarios designed for internal planning, investment evaluation, and procurement strategy. For teams that require defensible numbers, structured competitive context, and actionable market direction, the full study is the necessary reference point.
To access the complete dataset, segmentation detail, and full competitive profiles, visit the Proline Market research page on the PW Consulting platform. There, you can review the full scope of the analysis, evaluate the report against your internal planning requirements, and secure the intelligence needed to make 2026 and beyond decisions with confidence.
For detailed analysis of this topic, please visit the official page: Proline Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China Optical Sensing Market has exhibited consistent revenue growth from 2020 to 2025, driven by surge in demand for industrial automation, healthcare diagnostics, and smart city projects. Market revenue is forecast to accelerate further as smart manufacturing and digital health trends advance, surpassing USD 5,200 Million by 2025 and potentially reaching over USD 14,800 Million by 2035 amidst continuous technology adoption and production innovation.
Read More - https://bussinessinsights.com/research-report/china-optical-sensing-market
Healthcare remains the dominant application segment in China’s optical sensing market, propelled by rising deployment of biosensors and photonic devices in hospitals and research settings. The automotive sector is rapidly closing in, leveraging optical sensing for ADAS and autonomous vehicle technologies. Industrial applications are seeing accelerated adoption of distributed sensing solutions for process optimization. Consumer electronics contribute a significant share, emphasizing integration of miniature image sensors, while aerospace and defense applications maintain a niche but stable presence.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-optical-sensing-market
Frequently Asked Questions
Who are the key players in China Optical Sensing Market industry?
The top 5 players in the China Optical Sensing Market are Finisar Corporation, Oclaro Inc., Honeywell International Inc., Hamamatsu Photonics K.K., and Vishay Intertechnology, Inc. These companies excel in innovation, broad product portfolios, and strategic partnerships, driving advancements in optical sensors across telecommunications, healthcare, and automotive sectors.
What is the China Optical Sensing Market growth?
The China Optical Sensing Market is projected to grow at a CAGR of over 10% from 2023 to 2028, driven by increasing adoption of smart sensors in industrial automation and IoT devices. Recent investments by Honeywell in optical sensor manufacturing have further contributed to robust market growth.
Which segment accounted for the largest China Optical Sensing Market share?
Telecommunications applications hold the largest share of the China Optical Sensing Market. Growing demand for high-speed data transmission and expansion of 5G networks have led to increased deployment of optical sensors, especially for fiber optic communication and network monitoring solutions.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com